Home / Practice areas
Every case is different, but the goal is the same: make sure you are not left paying for someone else’s mistake. Choose your situation to see how I handle it.
Crashes with cars, SUVs and uninsured or underinsured drivers.
Semi trucks, delivery vans and other commercial vehicles.
Falls caused by unsafe floors, stairs or walkways.
The resale value your car lost after an accident.
The coverage I check on every case, including some you may not know you have.
Georgia is an at fault state, so the driver who caused the crash, and their insurer, is responsible for your losses. The catch is that their policy is often not enough. That is why I look at every source of recovery, including your own uninsured motorist and MedPay coverage.
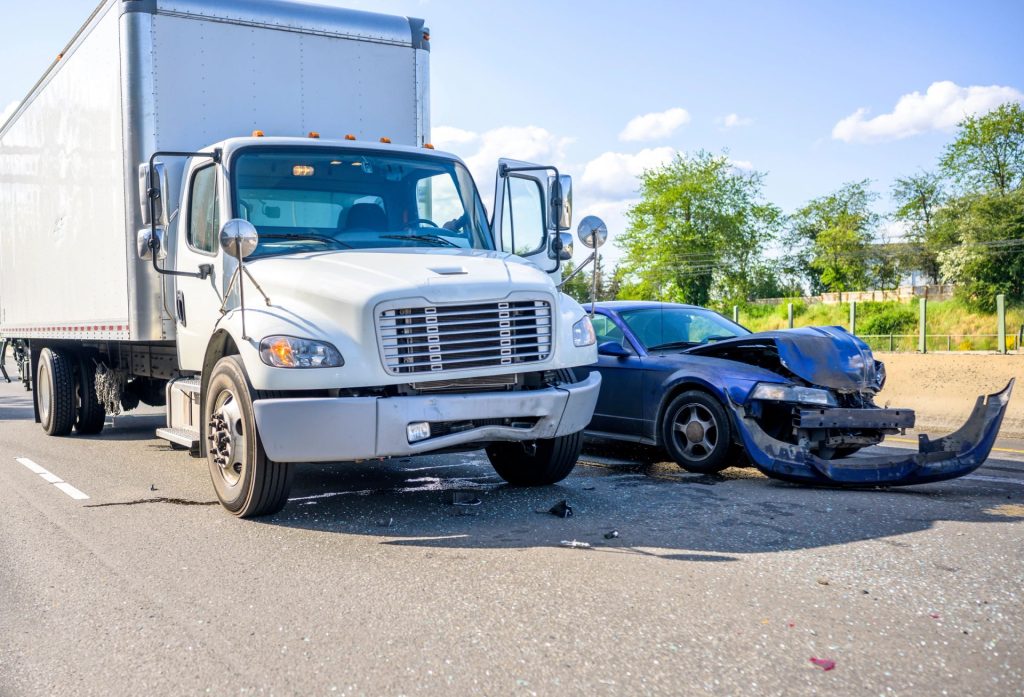
A crash with a semi truck or commercial vehicle is not a regular car wreck. Injuries tend to be more serious, more than one company can be responsible, and trucking insurers move fast. I move early to request records and preserve the evidence your case needs.
Stores, apartment complexes and other property owners must keep their property reasonably safe. When a wet floor, a broken stair or poor lighting causes a fall, they can be responsible. Photos, witness names and an incident report from the same day make a real difference.
A dog bite can mean stitches, infection, surgery and scars that stay with you. In many cases the owner’s homeowners or renters insurance covers the injury. I handle the claim so you can focus on healing.
Once a car has been in an accident, it is worth less at resale, even after perfect repairs. That lost value can be claimed. It generally applies to cars under 100,000 miles that are not too old. Send me your mileage and repair estimate, and I will tell you if a claim makes sense.
Medical payments coverage is an optional part of many auto policies. It pays medical bills no matter who caused the crash. It is commonly around $10,000, and I have seen it as high as $40,000. Using it means more of your settlement can go to you instead of to medical bills.
Uninsured and underinsured motorist coverage on your own policy can step in when the at fault driver’s coverage runs out or does not exist.
Possibly. If you live with a relative who carries their own auto or homeowners policy, you may qualify as a resident relative. I check this on every case.
Cars under 100,000 miles that are not too old are usually good candidates. Send me the year, mileage and repair estimate for a straight answer.
You do not need to figure it out alone. Send me the basics and I will tell you where you stand.
Attorney advertising. Sending this form does not create an attorney client relationship. Please do not send confidential information until we have spoken.